How Much Money
Do I Need
to Retire?
Retirement isn't about reaching one magic number. It's about understanding your future lifestyle, income needs, healthcare costs, inflation, and creating a strategy designed to support the retirement you envision.

Retirement Isn't About One Magic Number
Many people ask, "How much money do I need to retire?" While it's a common question, the answer is rarely a single dollar amount. Retirement planning is about understanding how your savings, income sources, lifestyle goals, healthcare costs, taxes, and inflation work together to support the life you want in retirement.
The Common Assumption
Many people believe retirement success is determined by reaching a specific savings goal—whether that's $500,000, $1 million, or another target. While building retirement savings is important, focusing on one number alone may overlook many other factors that influence long-term financial security.
A More Comprehensive Perspective
A thoughtful retirement strategy considers much more than savings alone. Future spending, retirement income sources, inflation, healthcare expenses, taxes, life expectancy, and unexpected events all play a role in determining whether your retirement resources align with your personal goals.
Lifestyle Goals
The retirement lifestyle you envision may influence your future income needs.
Healthcare Costs
Medical expenses often become a larger consideration during retirement.
Inflation
The purchasing power of today's dollars may change over time.
Taxes
Different income sources may have different tax considerations.
Longevity
Many retirement plans are designed with the possibility of a long retirement in mind.
Income Sources
Retirement income may come from multiple sources working together.
The 7 Factors That Shape Your Retirement Income Needs
Rather than focusing on a single savings target, many retirement plans begin by evaluating the factors that may influence future income needs. Understanding these considerations can help you develop a more informed retirement strategy.
Your Retirement Lifestyle
Do you envision traveling frequently, relocating, pursuing hobbies, or maintaining your current lifestyle? Your personal goals often influence future spending needs throughout retirement.
Healthcare Expenses
Healthcare costs may become a larger portion of retirement spending over time. Planning ahead for these potential expenses can be an important part of a comprehensive retirement strategy.
Inflation
Prices may increase over time, meaning today's income needs may differ from those you'll have years into retirement.
Life Expectancy
Many retirement plans are designed with the possibility of a retirement lasting several decades, making long-term planning an important consideration.
Retirement Income Sources
Income may come from several sources, including Social Security, retirement accounts, pensions, investments, and other financial resources.
Taxes
Different retirement income sources may have different tax implications. Understanding how taxes fit into your retirement strategy can be valuable.
Unexpected Life Events
Life rarely follows a perfect plan. Building flexibility into a retirement strategy may help you prepare for changing circumstances over time.
No Two Retirement Plans Are Exactly Alike
While calculators and retirement estimates can provide useful starting points, many retirement plans benefit from considering the full picture rather than relying on one number alone. Every individual's goals, circumstances, and priorities are different.
Building Your Retirement Income Blueprint
For many retirees, retirement income may come from multiple sources rather than a single account. Understanding how different income sources may work together can help create a more complete retirement strategy.
Social Security
For many individuals, Social Security serves as one component of retirement income. The amount received depends on individual circumstances and claiming decisions.
Retirement Investments
401(k)s, IRAs, brokerage accounts, and other investments may help support retirement income depending on your overall financial strategy.
Pensions
Some retirees receive pension income from current or former employers, providing another potential income source during retirement.
Guaranteed Income Strategies
Depending on an individual's goals and circumstances, some retirement strategies may include solutions designed to provide predictable income. The appropriateness of any strategy depends on individual needs and objectives.
Other Financial Resources
Savings, part-time employment, rental income, and other assets may also contribute to retirement income for some individuals.
A Strong Retirement Strategy Often Brings Multiple Pieces Together
Rather than relying on a single source of income, many retirement strategies evaluate how different resources may complement one another over time. The right approach depends on your personal goals, financial circumstances, and retirement objectives.
Could Your Retirement Plan Answer These Questions?
One way to evaluate your retirement preparedness is to ask yourself a few important questions. While there are no universal answers, understanding these topics may help identify areas where additional planning could be beneficial.
How much monthly income will I actually need?
Retirement planning often begins with understanding expected monthly expenses rather than focusing solely on accumulated savings.
How will inflation affect my retirement over the next 20–30 years?
The purchasing power of today's income may change over time, making inflation an important planning consideration.
What happens if healthcare costs are higher than expected?
Healthcare expenses may become a larger part of retirement spending and should be considered within a broader retirement strategy.
Where will my retirement income come from each month?
Many retirees receive income from multiple sources rather than relying on one account or one benefit.
Will my current savings support the lifestyle I hope to enjoy?
Your retirement goals and expected spending habits often influence the amount of income needed throughout retirement.
When was the last time I reviewed my retirement strategy?
Many people revisit their retirement plans periodically as their financial circumstances and personal goals evolve.
There Are No Perfect Answers
These questions are intended to encourage thoughtful retirement planning—not to create concern. Every retirement journey is different, and understanding your personal goals, financial circumstances, and available options is an important step toward making informed decisions.
The Retirement Income Pyramid
Many retirement strategies involve more than one income source. This illustration shows how different resources may support different aspects of retirement planning. The exact mix depends on your personal goals, financial circumstances, and retirement objectives.
Your Ideal Retirement Lifestyle
Travel • Family • Giving • Hobbies • Experiences
Flexible Lifestyle Spending
Entertainment • Dining • Vacations • Special Purchases
Retirement Savings & Investments
401(k) • IRA • Investment Accounts • Personal Savings
Reliable Income Sources
Social Security • Pension (if applicable) • Other Predictable Income
Essential Living Expenses
Housing • Utilities • Food • Healthcare • Insurance
Why This Framework Matters
Rather than relying on a single account or one income source, many retirement plans evaluate how multiple resources may work together. Essential expenses are often considered differently from discretionary spending, helping create a more flexible retirement strategy.
- Focus on one savings goal
- Limited income flexibility
- Little planning for inflation
- Unclear spending priorities
- Multiple potential income sources
- Income matched to priorities
- Long-term planning considerations
- Regular review as life changes
7 Retirement Planning Mistakes to Avoid
No retirement plan is perfect, and everyone's circumstances are different. However, understanding some of the more common planning challenges may help you ask better questions and prepare for the years ahead.
Focusing Only on Savings
Retirement planning is about more than reaching a savings goal. Future income needs, spending patterns, healthcare costs, taxes, and inflation also play an important role.
Underestimating Healthcare Costs
Medical expenses may become a larger part of retirement spending than many people anticipate. Planning ahead may help reduce unexpected financial pressure.
Ignoring Inflation
Even modest inflation may reduce purchasing power over time, making long-term planning an important consideration.
Not Reviewing the Plan
Retirement planning is an ongoing process. Reviewing your strategy periodically allows it to evolve alongside changes in your goals and financial circumstances.
Relying on One Income Source
Many retirement plans consider how multiple income sources may work together rather than depending on a single account or benefit.
Forgetting About Taxes
Different retirement income sources may have different tax considerations that could affect overall retirement income.
Waiting Too Long to Start Planning
Beginning retirement planning earlier often provides more flexibility, but reviewing your strategy at any stage may still provide valuable insights.
Preparation Begins With Asking the Right Questions
Understanding potential planning challenges doesn't mean they'll occur. Instead, recognizing these topics may help you make more informed retirement planning decisions and prepare for future financial needs.
How Retirement Ready Do You Feel?
While no checklist can fully measure retirement preparedness, reflecting on these questions may help you identify areas where additional planning or education could be beneficial.
Retirement Readiness Scorecard
Review each statement below and simply ask yourself: "Can I confidently answer yes?"
Every Retirement Journey Is Different
This checklist is intended for educational purposes only and is not a financial assessment. Retirement planning should consider your individual goals, financial circumstances, and personal priorities.
Common Retirement Questions Answered by Dan
For nearly four decades, Dan Rosenberg has helped individuals and families better understand retirement planning. Below are educational responses to some of the questions he hears most often from people preparing for retirement.
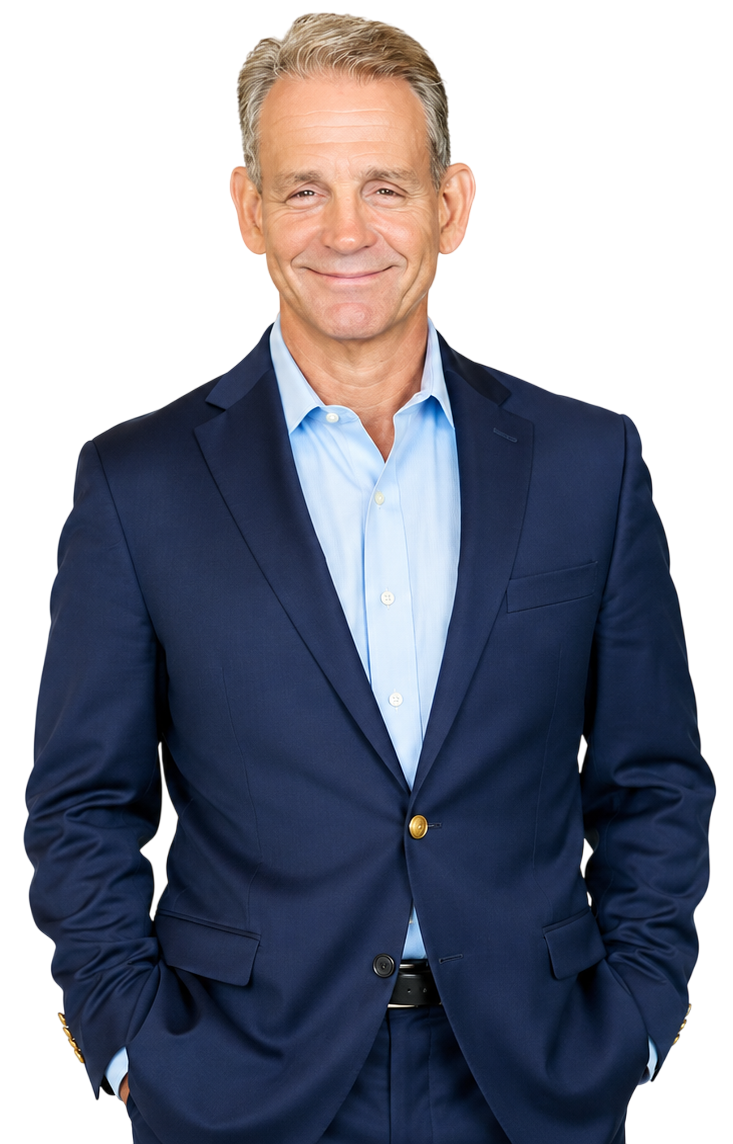
A Message From Dan
"Throughout my career, I've learned that successful retirement planning rarely begins with finding the perfect investment. It begins by understanding your goals, asking thoughtful questions, and creating a strategy designed around the retirement you want to enjoy."
Certified Financial Fiduciary®
CLU | ChFC
Is there a specific amount everyone should have before retiring?
There isn't one retirement savings amount that's appropriate for everyone. Retirement income needs vary based on lifestyle goals, expected expenses, healthcare costs, taxes, inflation, longevity, and the resources available to each individual.
Should I be worried about running out of money during retirement?
This is one of the most common questions I hear. While no one can predict the future with certainty, understanding your income sources, expected spending, and retirement objectives may help you prepare more confidently for the years ahead.
When should I begin retirement planning?
Starting earlier often provides more flexibility, but it's never too late to review your retirement strategy. Many people benefit from revisiting their plans as their goals, finances, and priorities evolve over time.
How often should I review my retirement strategy?
Many individuals review their retirement plans annually or after significant life events such as retirement, changes in health, family circumstances, or major financial changes. Regular reviews can help ensure your strategy continues to reflect your goals.
Your Retirement Starts With a Plan, Not Just a Number
One of the biggest misconceptions about retirement planning is believing success depends on reaching a specific savings goal. While saving is important, retirement is ultimately about creating a strategy that supports the life you hope to live.
Your retirement journey may include decisions about income sources, healthcare expenses, taxes, inflation, Social Security, investment withdrawals, and lifestyle priorities. Because every individual and family has different goals, retirement planning is rarely one-size-fits-all.
The most valuable retirement plan isn't necessarily the one with the highest account balance—it's the one designed around your personal objectives and reviewed as life changes over time.
Remember These Four Ideas
Ready to Continue the Conversation?
Retirement planning is personal. Every individual's goals, financial circumstances, and priorities are different. If this guide has raised questions or you'd like to better understand your retirement planning options, we're here to help.
Introductory Conversation
Speak with a member of our team about your retirement goals, current situation, and the questions you have after reading this guide.
Learn About Our Process
We'll explain how Rosenberg Wealth Management approaches retirement planning and answer general questions about what to expect moving forward.
Determine the Appropriate Next Step
If appropriate, we'll help coordinate a meeting with Dan Rosenberg to discuss your retirement planning goals in greater detail.
There is no obligation to move forward. The introductory call is intended to learn about your goals, answer general questions about our process, and determine whether a meeting with Dan would be appropriate based on your individual circumstances.
This guide is provided for educational purposes only and should not be considered individualized financial, investment, tax, or legal advice. Any recommendations, if appropriate, would only be made after a review of your personal financial situation and objectives.