You Don't Have to
Figure Out Your
Annuity Alone.
Annuities can be complex. Understanding how they work, what they provide, what they cost, and how they fit into your retirement strategy can help you make more informed decisions.
Schedule a Qualification Call →What Is an Annuity?
Understanding the fundamentals is the first step toward making informed retirement planning decisions.
An annuity is a financial product issued by an insurance company that may help provide income during retirement. Depending on the type of annuity selected and the terms of the contract, it may offer features designed to support long-term retirement income planning.
Annuities come in several forms, each with unique characteristics, benefits, limitations, and considerations. Some focus on principal protection, others provide income options, while certain contracts include optional features designed to address specific retirement objectives.
Understanding how annuities work—and how they compare with other retirement planning strategies—is an important part of making informed financial decisions.
Key Takeaways
- Issued by insurance companies
- May provide retirement income
- Available in multiple contract types
- Can include optional riders and features
- Should be evaluated as part of an overall retirement strategy
- Not appropriate for every investor or financial situation
How Do Annuities Work?
Although every annuity contract is different, most follow a similar process. Understanding these stages can help you better evaluate how an annuity may fit within your retirement income strategy.
Purchase
An annuity is purchased from an insurance company using either a lump-sum payment or a series of contributions, depending on the contract.
Accumulation
During the accumulation period, the contract may grow based on the provisions of the annuity and the terms established by the insurance company.
Income
When income begins, the annuity may provide scheduled payments according to the payout option selected within the contract.
Retirement
Depending on your overall financial plan, annuity income may complement other retirement income sources such as Social Security, pensions, investments, and personal savings.
Types of Annuities
There is no single type of annuity that is appropriate for everyone. Each type offers different features, objectives, and considerations. Understanding these differences can help you evaluate which options may align with your retirement goals and overall financial strategy.
Fixed Annuity
Fixed annuities generally provide a stated interest rate for a specified period according to the contract. They are often considered by individuals seeking stability and predictable growth.
Fixed Indexed Annuity
Interest crediting is linked to the performance of a market index, subject to contract provisions such as participation rates, spreads, and caps. Contract owners do not directly invest in the market index.
Variable Annuity
Variable annuities allow contract values to fluctuate based on the performance of selected investment options. Investment risk is generally assumed by the contract owner.
Immediate Annuity
Immediate annuities generally begin income payments shortly after purchase according to the payout option selected within the contract.
Deferred Annuity
Deferred annuities are designed to accumulate value before future income payments begin, allowing retirement income to start at a later date.
Optional Riders
Some annuity contracts offer optional riders that may provide additional income, death benefit, or other features. Availability and costs vary by insurance company and contract.
Potential Benefits and Important Considerations
Every financial strategy involves trade-offs. Annuities may offer valuable features for certain retirement planning objectives, but they also involve important considerations. Understanding both sides helps you make more informed decisions.
Potential Benefits
Retirement Income
Depending on the contract selected, certain annuities may provide income options designed to help support retirement cash flow.
Tax-Deferred Growth
Some annuities allow earnings to grow tax-deferred until withdrawals begin, subject to applicable tax laws.
Principal Protection Options
Certain annuity contracts include features intended to help protect principal from market declines, subject to contract provisions.
Guaranteed Income Features
Some contracts offer optional lifetime income features backed by the claims-paying ability of the issuing insurance company.
Retirement Planning Flexibility
Annuities may complement Social Security, pensions, investments, and other retirement income sources as part of a broader financial strategy.
Important Considerations
Long-Term Commitment
Many annuities are designed as long-term financial products and may not be appropriate for every investor.
Surrender Periods
Certain contracts include surrender periods during which withdrawals above permitted amounts may result in charges.
Fees and Expenses
Depending on the annuity type and optional features selected, fees and other contract expenses may apply.
Liquidity Needs
Individuals should consider their need for access to funds before purchasing any long-term financial product.
Individual Suitability
Annuities are not appropriate for every financial situation. Any decision should be based on your individual goals, financial circumstances, and retirement objectives.
Our Educational Philosophy
At Rosenberg Wealth Management, we believe retirement planning begins with understanding—not pressure. Every client deserves clear explanations, thoughtful guidance, and the opportunity to evaluate available options before making important financial decisions.
Who Might Consider an Annuity?
Every retirement journey is unique. Annuities are not designed for everyone, but they may be appropriate for certain individuals depending on their retirement goals, income needs, financial circumstances, and overall strategy.
Individuals Approaching Retirement
Those nearing retirement often begin evaluating strategies that may help create a reliable source of retirement income while balancing other financial priorities.
Retirees Seeking Income
Some retirees explore annuities as one possible component of an overall retirement income strategy alongside Social Security, pensions, investments, and other assets.
Long-Term Planners
Individuals focused on long-term financial planning may consider annuities as one of several available tools when developing a retirement income plan.
Conservative Investors
Certain annuity products may appeal to individuals seeking features designed to reduce market exposure while maintaining long-term retirement objectives.
Families Planning for the Future
Depending on the contract, certain annuities include beneficiary options and other features that may support broader financial planning discussions.
People Looking for Professional Guidance
Many individuals simply want help understanding their retirement options before making important financial decisions. Education is often the best place to begin.
The Right Strategy Depends on You
No financial product is appropriate for every investor. The suitability of an annuity depends on factors such as your retirement timeline, financial objectives, liquidity needs, risk tolerance, tax considerations, and overall retirement strategy. A thoughtful review of your individual circumstances is an important part of making informed financial decisions.
Separating Fact from Fiction
Annuities are often misunderstood. Misinformation can make it difficult to evaluate whether an annuity deserves consideration as part of a retirement income strategy. Here are a few common misconceptions and the facts behind them.
❌ Myth: All annuities are the same.
Fact: There are several types of annuities, each with different objectives, contract provisions, risks, benefits, and costs. Understanding the differences is an important part of making informed decisions.
❌ Myth: Annuities are only for retirees.
Fact: Some individuals begin evaluating annuities years before retirement as part of a broader long-term retirement income strategy. Suitability depends on personal circumstances and financial objectives.
❌ Myth: Every annuity has high fees.
Fact: Costs vary significantly depending on the type of annuity and optional features selected. Some annuities have limited ongoing expenses, while others may include fees associated with investment options or optional riders.
❌ Myth: You'll lose access to your money.
Fact: Many annuity contracts provide withdrawal provisions, although surrender charges or contract limitations may apply. It is important to understand the liquidity features before purchasing any contract.
❌ Myth: Annuities replace all other investments.
Fact: Annuities are generally considered one potential component of a diversified retirement strategy. Whether an annuity is appropriate depends on your financial goals, income needs, risk tolerance, and overall retirement plan.
❌ Myth: Buying an annuity is the first step in retirement planning.
Fact: Retirement planning should begin with understanding your goals, income needs, assets, liabilities, and long-term objectives. Any financial product should be evaluated only after considering your overall financial picture.
Education Leads to Better Decisions
Retirement planning isn't about finding a one-size-fits-all solution. It's about understanding your options, asking informed questions, and evaluating strategies that align with your unique financial goals. Education is the foundation of every meaningful financial decision.
Answers to Common Questions About Annuities
Below are answers to some of the questions individuals frequently ask when learning about annuities and retirement income planning.
What is an annuity?
An annuity is a financial product issued by an insurance company that may provide retirement income or other features depending on the contract selected.
How do annuities work?
Generally, an annuity is purchased from an insurance company. Depending on the contract, it may accumulate value before future income begins or provide income shortly after purchase.
What types of annuities are available?
Common types include fixed, fixed indexed, variable, immediate, and deferred annuities. Each type has different objectives, features, risks, and considerations.
Can annuities provide lifetime income?
Certain contracts offer income options designed to provide payments for life. Guarantees are subject to the claims-paying ability of the issuing insurance company.
Are annuities taxable?
Tax treatment depends on the type of annuity, ownership, and distribution method. Individuals should consult a qualified tax professional regarding their specific situation.
Can I withdraw money from an annuity?
Many contracts permit withdrawals under certain conditions. Surrender charges, tax consequences, or other limitations may apply depending on the contract.
Are annuities FDIC insured?
No. Annuities are insurance products and are not insured by the Federal Deposit Insurance Corporation (FDIC). Contract guarantees are backed by the claims-paying ability of the issuing insurance company.
Can annuities be part of an overall retirement strategy?
Depending on an individual's financial objectives and circumstances, an annuity may be one component of a broader retirement income strategy.
Should everyone own an annuity?
No. Annuities are not appropriate for every investor. Suitability depends on individual goals, liquidity needs, risk tolerance, retirement timeline, and other financial considerations.
How do I know whether an annuity is appropriate for me?
Evaluating an annuity involves reviewing your retirement goals, income needs, assets, tax considerations, and long-term financial objectives with a qualified financial professional.
Experience Matters When Planning Your Retirement
Retirement planning is about more than selecting financial products. It involves understanding your goals, evaluating available options, and developing a strategy that reflects your unique financial circumstances.
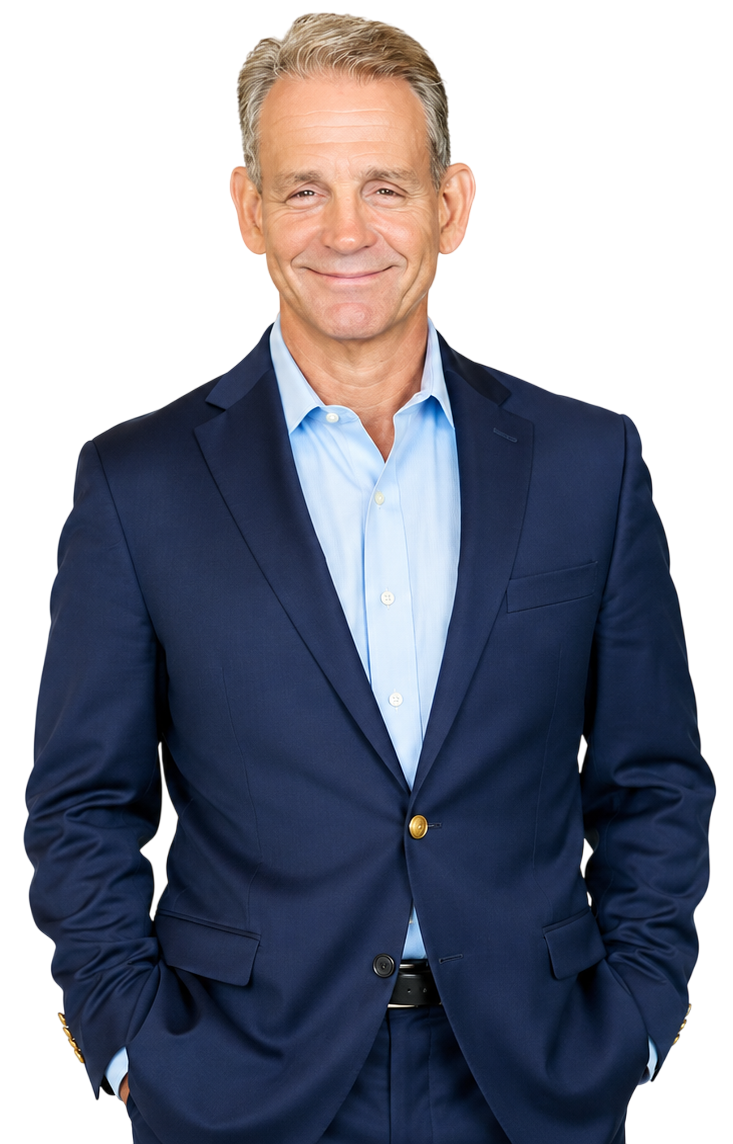
For more than four decades, Dan Rosenberg has worked with individuals and families to help them navigate important retirement decisions through education, thoughtful planning, and personalized guidance.
His approach begins by listening. Every recommendation is built around understanding each client's retirement goals, income needs, time horizon, and long-term financial objectives before discussing potential strategies.
Nearly 40 Years
Helping clients prepare for retirement.
Education First
Clear explanations before important decisions.
Personal Guidance
Retirement strategies tailored to individual goals.
Long-Term Relationships
Built on trust, communication, and service.
"The best retirement decisions begin with understanding your options."
Ready to Take the Next Step?
You've taken the time to learn about annuities and retirement income planning. If you'd like to discuss your retirement goals, review your current strategy, or ask questions about the information you've explored, we're here to help.
Every retirement plan is unique. Your introductory consultation is an opportunity to discuss your financial objectives, ask questions, and determine the most appropriate next steps. If additional planning is appropriate, we'll coordinate a personalized meeting with Daniel Rosenberg.
Schedule
Select a convenient time for your introductory retirement consultation.
Connect
We'll learn about your goals, answer your initial questions, and better understand your retirement planning priorities.
Plan
If appropriate, we'll coordinate the next steps, including a meeting with Daniel Rosenberg to discuss your retirement strategy.
Schedule Your Initial Retirement Consultation
Choose a convenient time to begin the conversation.
Schedule My ConsultationThe information provided on this website is intended for educational purposes only and should not be considered individualized financial, investment, tax, or legal advice. Every retirement strategy should be evaluated based on your individual goals, financial circumstances, and overall planning objectives.